Term vs. Whole Life Insurance: Making the Right Choice
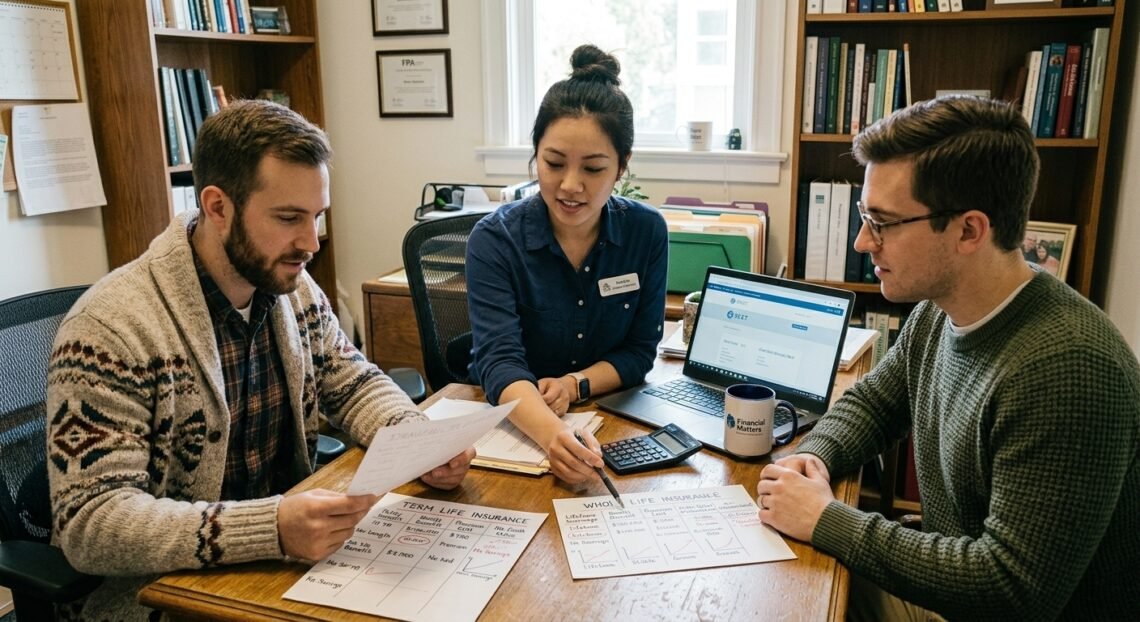
Choosing the right life insurance policy is one of the most important financial decisions you can make to protect your family’s future. The market generally splits options into two main categories: term life and whole life insurance. Understanding their structural differences, costs, and benefits is key to finding the right fit.
1. Term Life Insurance: Simple and Affordable
Term life insurance provides coverage for a specific period—typically 10, 20, or 30 years. It is pure protection designed to replace income or cover major debts during your peak earning and child-rearing years.
- How it Works: You pay a fixed monthly or annual premium for the chosen term. If you pass away during that window, your beneficiaries receive the tax-free death benefit. If you outlive the term, the policy expires with no payout.
- Key Advantage: Exceptional affordability. Because it is temporary and carries no investment component, you can secure high coverage amounts (such as 10 to 12 times your annual income) for a very low cost.
- Best For: Budget-conscious families, replacing income while children are at home, or covering a long-term mortgage.
2. Whole Life Insurance: Lifelong Security and Equity
Whole life insurance is a form of permanent coverage that remains active for your entire life, provided you continue paying the premiums. It combines a guaranteed death benefit with a savings element known as cash value.
- How it Works: Premiums are significantly higher than term policies, but they remain level for life. A portion of each payment goes toward administrative costs and the death benefit, while the remainder builds tax-deferred cash value that grows at a guaranteed rate. You can borrow against this cash value or withdraw from it while you are alive.
- Key Advantage: Permanence and forced savings. It never expires, and policies from mutual insurance companies may also pay annual dividends to further boost your cash value.
- Best For: Individuals with lifelong dependents (such as a child with special needs), estate planning liquidity, or high earners who have already maximized traditional retirement accounts.
Key Comparison Breakdown
| Feature | Term Life Insurance | Whole Life Insurance |
| Duration | Set period (10–30 years) | Entire lifetime |
| Cost | Low initial premiums | High, level premiums |
| Cash Value | None | Yes, builds tax-deferred equity |
| Primary Goal | Temporary income replacement | Permanent legacy & asset building |
Which Should You Choose?
For the vast majority of people, term life insurance is the most practical choice because it maximizes protection when financial responsibilities are highest. However, if you have complex estate needs or permanent financial obligations, whole life provides unique structural advantages.
Would you like to calculate how much term life coverage your current income and family obligations require?