The Great Coverage Debate: Term vs. Whole Life Insurance
Few financial products trigger as much head-scratching—or heated debate—as life insurance. Step into any personal finance forum, and you will find people divided into two enthusiastic camps: those who swear by the affordable, straightforward protection of Term Life, and those who value the permanent coverage and built-in cash value of Whole Life.
When you strip away the aggressive sales pitches and glossy marketing brochures, choosing between these two options comes down to a fundamental question: What problem are you actually trying to solve?
Term Life Insurance: Pure Protection on a Budget
Think of Term Life insurance like renting an apartment. You pay a predictable monthly rate for a set amount of time—typically 10, 20, or 30 years. If you pass away while the policy is active, your beneficiaries receive a tax-free payout (the death benefit). If the policy term ends and you are still breathing, the coverage simply expires, and you walk away with nothing extra.
Because you are paying only for the insurance risk—without any investment bells and whistles—Term Life offers maximum coverage for a minimal price tag.
Why Term Life Works for Most People
- Affordability: A healthy 30-year-old can often get a 20-year, $500,000 policy for less than $30 a month.
- Income Replacement: It covers your highest-earning years when young children depend on your income, or when you hold a 30-year mortgage.
- Simplicity: No hidden fee structures, surrender charges, or market performance metrics to track.
Whole Life Insurance: Permanent Coverage with Cash Value
If Term Life is renting, Whole Life is like buying a condo. It stays in effect for your entire lifespan (as long as premiums are paid), and a portion of every monthly payment goes toward building cash value—a tax-deferred savings account attached to the policy that grows at a guaranteed rate set by the insurer.
Eventually, you can borrow against that cash value, pull money out for retirement, or use it as collateral for a loan. However, this permanence and cash-building mechanism comes with a steep price tag: monthly premiums for Whole Life can run 5 to 10 times higher than a Term policy with the exact same death benefit.
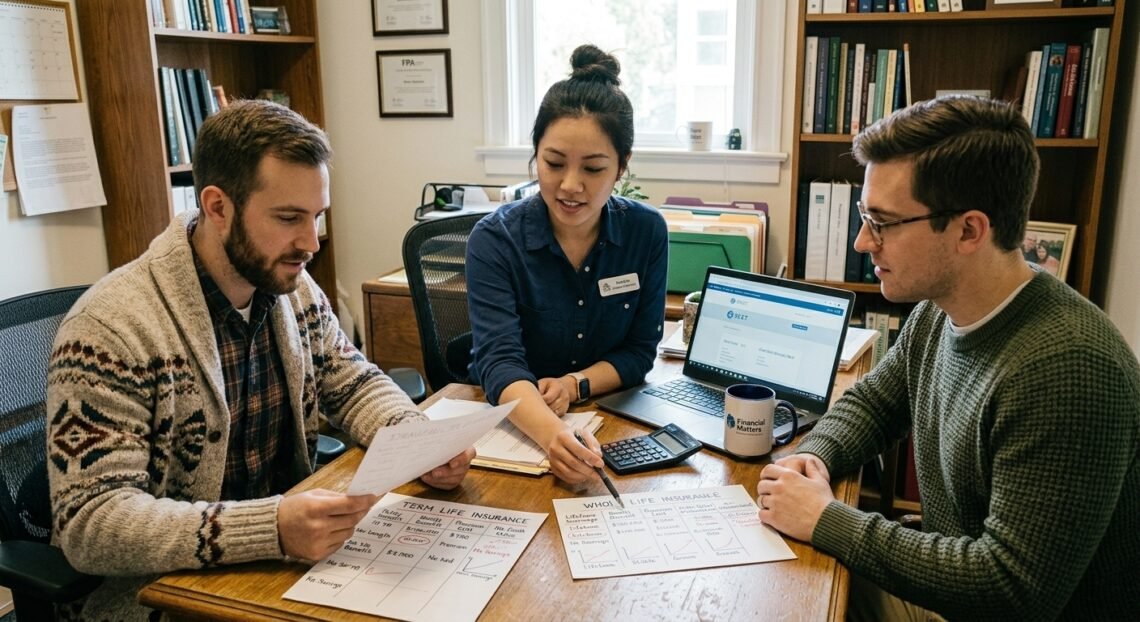
| Feature | Term Life Insurance | Whole Life Insurance |
| Coverage Duration | Set period (10–30 years) | Permanent (Lifelong) |
| Monthly Cost | Low and fixed for the term length | Significantly higher (5–10x Term) |
| Cash Value Growth? | No | Yes (Grows at a guaranteed rate) |
| Best Used For… | Income replacement, raising kids, mortgages | Estate planning, lifelong dependents, high-net-worth tax strategies |
Running the Real-World Cost Comparison
To see how the numbers stack up in practice, consider two common financial paths over a 20-year stretch:
Option A: Buy Term + Invest the Difference in standard index funds
Option B: Buy Whole Life + Rely on the Policy's Cash Value growth
Because Term premiums are so much lower, taking the money you save on monthly premiums and investing it directly into low-cost index funds (like an S&P 500 ETF) routinely yields higher total returns over 20 to 30 years than a Whole Life cash-value growth rate.
However, Whole Life provides a guaranteed return and a guaranteed payout regardless of when you pass away, which appeals to risk-averse individuals who want absolute certainty rather than market fluctuation.
How to Decide Which Policy Fits Your Life
Choosing the right insurance structure depends on where you are in your career, your family responsibilities, and your overall estate structure:
- Choose Term Life if: Your primary goal is protecting your family while you pay down a mortgage, raise children, or build up your retirement nest egg. Once your kids are independent and your investments are established, you may no longer need life insurance coverage.
- Choose Whole Life if: You have a lifelong financial obligation—such as a child with special needs who will require lifelong care—or you have maxed out all standard retirement accounts (401k, IRA, Roth IRA) and want a tax-advantaged vehicle for estate planning or business succession.
Before signing any long-term contract, review your total household budget, estimate the exact financial gap your family would face if your income vanished tomorrow, and lock in coverage early while youth and good health are on your side.