The Uninsurable Reality: How Climate Change Is Rewriting Property Insurance
For decades, property insurance operated on a quiet, predictable rhythm. Actuaries examined historical weather data, calculated local risk probabilities, set reasonable premiums, and paid out claims when an occasional seasonal storm damaged a roof or flooded a basement. It was a stable model built on a reliable premise: extreme weather events were rare anomalies scattered across time and space.
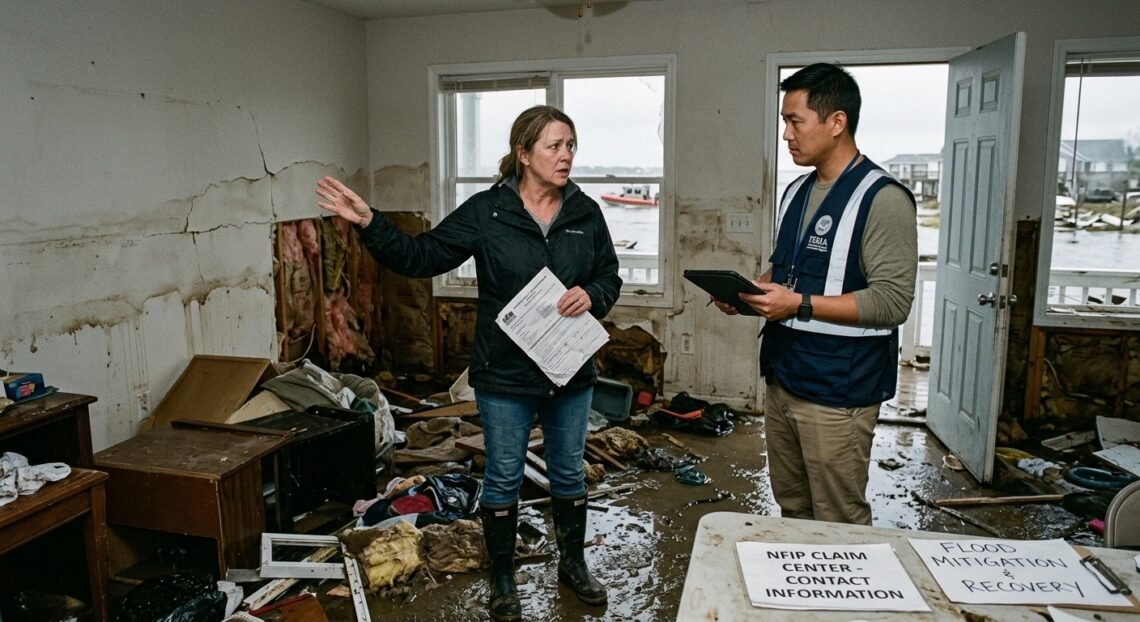
That calm equilibrium is officially over. Today, rapidly shifting climate patterns—manifesting as intense wildfires, severe hail storms, record hurricane seasons, and sudden flash floods—are shattering traditional financial models. As a result, home and commercial property insurance is shifting from a routine household expense into an urgent national crisis.
The Death of Historical Risk Modeling
The fundamental issue facing property insurance carriers is simple: the past is no longer a reliable predictor of the future.
Historically, an underwriter looked back over 50 to 100 years of weather records to price a policy for the coming year. But when atmospheric temperatures rise, severe weather scales exponentially rather than linearly. “Once-in-a-century” floods now hit the same river basins every three to five years, and wildfires burn deeper into suburban communities that were previously considered zero-risk zones.
When insurers can no longer accurately price risk using historical tables, they protect themselves in two ways: raising annual premiums dramatically or withdrawing from high-risk postal codes altogether.
Catastrophe Premium Rate = (Base Property Risk + Climate Exposure Factor) × Reinsurance Multiplier
Major carriers have quietly pulled back from entire states, leaving homeowners scrambling for high-cost state-backed “insurers of last resort” that offer far skimpier coverage for double or triple the price.
How Reinsurance Compounds the Problem
Most homeowners do not realize that insurance companies buy insurance for themselves. These backstop institutions, known as reinsurers, absorb the massive financial blows when a major hurricane or wildfire generates billions in simultaneous claims.
| Market Level | Role | Current Climate Reality |
| Primary Insurer | Issues policy directly to homeowner | Facing insolvency risk from localized, frequent severe weather events |
| Reinsurer | Protects primary insurers against multi-billion dollar losses | Raising rates globally by 20% to 50% due to consecutive high-payout years |
| State Programs | Backstop pools for uninsurable properties | Swollen with record policy volumes, risking taxpayer-funded bailouts |
Because reinsurers operate globally, a catastrophic winter storm in Europe or a flood in Asia increases capital costs worldwide. Primary insurers pass those escalating reinsurance costs straight down to everyday policyholders in their monthly mortgage escrow statements.
The Rising Gap Between Market Value and Insurance Valuation
A subtle trap facing homeowners today is the distinction between a property’s market value and its reconstruction cost. Supply chain bottlenecks, labor shortages, and rising building material costs—often triggered by regional post-disaster demand spikes—mean rebuilding a damaged home costs vastly more today than it did five years ago.
If an insurer caps coverage based on outdated construction rates, a homeowner facing a total loss from a wildfire or severe storm might discover a six-figure shortfall between their payout and the actual cost to rebuild a code-compliant house.
Practical Steps to Protect Your Property and Policy
While individuals cannot control global weather trends, property owners can take concrete steps to maintain coverage and keep premiums manageable:
- Invest in Physical Hardening: Install fire-resistant roofing, clear defensible space around structures, add storm shutters, and fit backwater valves on plumbing lines. Many insurers offer premium discounts for verifiable mitigation steps.
- Audit Policy Exclusions Annually: Standard homeowners policies almost universally exclude flood damage and ground movement. If you live near water or on slopes, secure separate flood or landslide endorsements before storm season begins.
- Explore Higher Deductibles Wisely: Selecting a higher percentage-based wind or hurricane deductible reduces your monthly costs, but ensure you maintain an emergency reserve capable of absorbing that higher out-of-pocket expense if a disaster strikes.